
On August 10, 2026, the FDIC announced an updated process for reviewing new federal deposit insurance applications. The revised procedures, issued through Financial Institution Letter (FIL) 48-2026 and applicable to applications received after August 15, 2026, restructures the agency’s review of applications into a defined two-phase framework for de novo applicants that satisfy relevant application requirements:
- A contingent authorization within 120 days of receiving the application.
- Approval within the subsequent 12 months once organizational and pre-opening steps are complete.
The revised procedures are intended to encourage new bank formation, accelerate the speed of the review process, and improve the efficiency of the application process. While the revisions matter less for what the FDIC asks of applicants, and more for when it asks for it, they mark a clearer path for applicants.
A Statutory Mandate, Not a Standalone Policy
The reform did not emerge in isolation and is consistent with other revisions. The FDIC describes its revised procedures as generally consistent with the 21st Century ROAD to Housing Act (Act), enacted on July 11, 2026. The Act pairs a broad housing supply agenda with a set of community banking provisions. Among these provisions are instructions to the federal banking agencies to review and streamline the de novo application process.
Congress highlighted new bank formation as a housing and credit access issue. The throughline is that a thinning population of community banks constrains local lending that finances homeownership, construction, and small business. Additional provisions in the Act expand the reciprocal and custodial deposit carve-outs from brokered deposit treatment and raise the asset threshold for the extended examination cycle from $3 billion to $6 billion. In addition, the Act establishes a financial agent mentor-protégé program, pairing large commercial banks with small, minority, or rural financial institutions.
Importantly, the Act authorizes a pilot two-year phase-in of capital standards for qualifying de novo community banks and permission for de novo community banks to deviate from an approved business plan during the first two years without automatically triggering regulatory concern. Together, these provisions aim to lower the cost and friction of forming and sustaining a community bank.
Read together with the FDIC’s revised procedures, the statute and the agency action signal a coordinated federal posture to support new community bank formation.
Phase One: The Contingent Authorization Phase
Phase one runs 120 calendar days from the FDIC’s receipt of a substantially complete application. During this window, the FDIC evaluates the core merits of the proposal. The following content is expected with the initial submission of the application:
- Business plan that provides a market and competitive analysis, customer demographics, anticipated products and services, the planned office/branch structure, and any other pertinent items;
- Financial projections with supporting assumptions for the first three years of operations, along with appropriate sensitivity analyses and/or stress testing. Projections should include quarterly and year-end data and key ratios and should also cover the parent organization where applicable. A proposed subsidiary of an existing organization must also supply that organization’s financial statements for the current period and prior three years;
- Complete ownership and organizational structure, including affiliates and any foreign ownership, as applicable;
- A description of the planned capital raise, the amount of capital needed to support the business plan, any known or anticipated investor commitments, and a draft offering circular if available;
- The identity of the proposed CEO, any other senior executive officers (if known), and any board members (if known). Further, an Interagency Biographical and Financial Report (IBFR) for each known director, senior executive officer, and principal shareholder;
- Details regarding the proposed senior executive officer positions and an outline of preliminary compensation plans, if known;
- A description of any contract, transaction, professional fees, or other type of planned business relationship involving the proposed institution and its parent company, affiliates, or any insider, including shared services;
- A list of the functions/services to be outsourced, and a list of the functions/services that will be performed internally;
- Copies of any related applications filed or planned to be filed with other regulatory agencies; and
- A copy of the public notice.
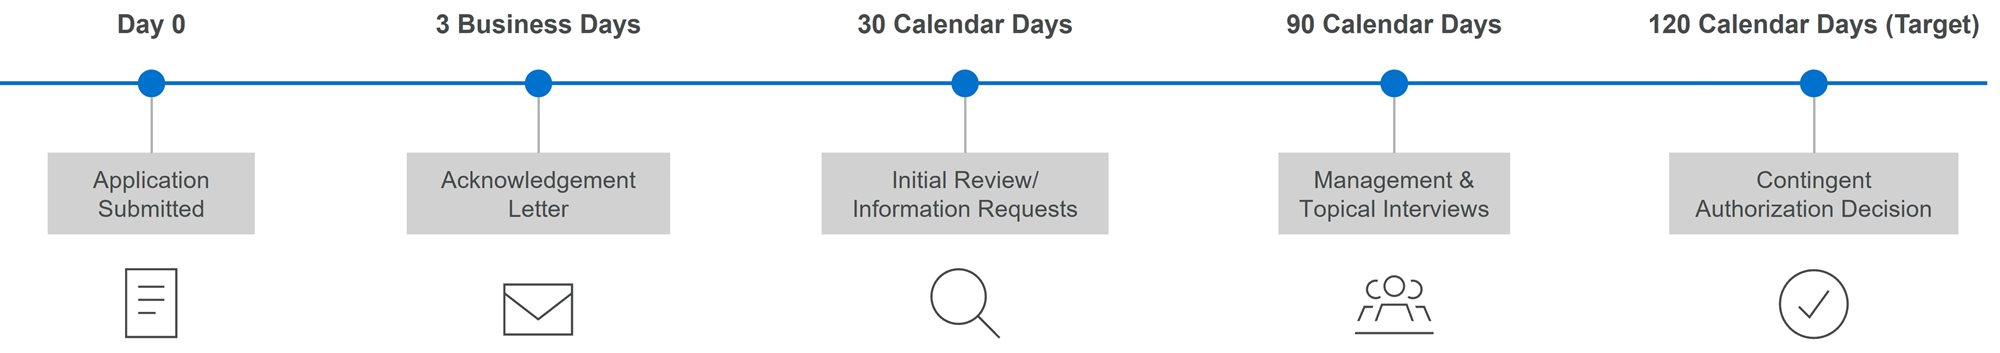
Phase one has several interim milestones. The FDIC will send an acknowledgment letter within three business days of the receipt of the application. Within 30 calendar days the agency reviews the filing, communicates with organizers on completeness, and issues an additional information request if necessary. Within 90 calendar days, FDIC and other agency representatives meet with the organizers for initial management and topical interviews, coordinated with the chartering authority and the appropriate Federal Reserve office where possible. It is important to note, a contingent authorization is a conditional signal, not a grant of deposit insurance.
Phase Two: The Organizational Phase
Phase two begins immediately upon contingent authorization and may last up to 12 months. During this phase, the organizing group completes the work of standing up the institution, including executing the capital raise, finalizing affiliate agreements, contracting vendors, selecting office and branch locations, finalizing employment and compensation agreements, building risk management and compliance programs, and preparing Community Reinvestment Act (CRA) plans, among other items. The FDIC then seeks the applicant’s written agreement to all proposed conditions and issues a transmittal letter with the deposit insurance order. Following the order, and within six months of approval, the applicant must provide confirmation that pre-opening conditions have been satisfied. The FDIC will complete a pre-opening examination within 30 days ahead of the proposed opening date, and, following the successful results of the examination, the deposit insurance certificate is issued.
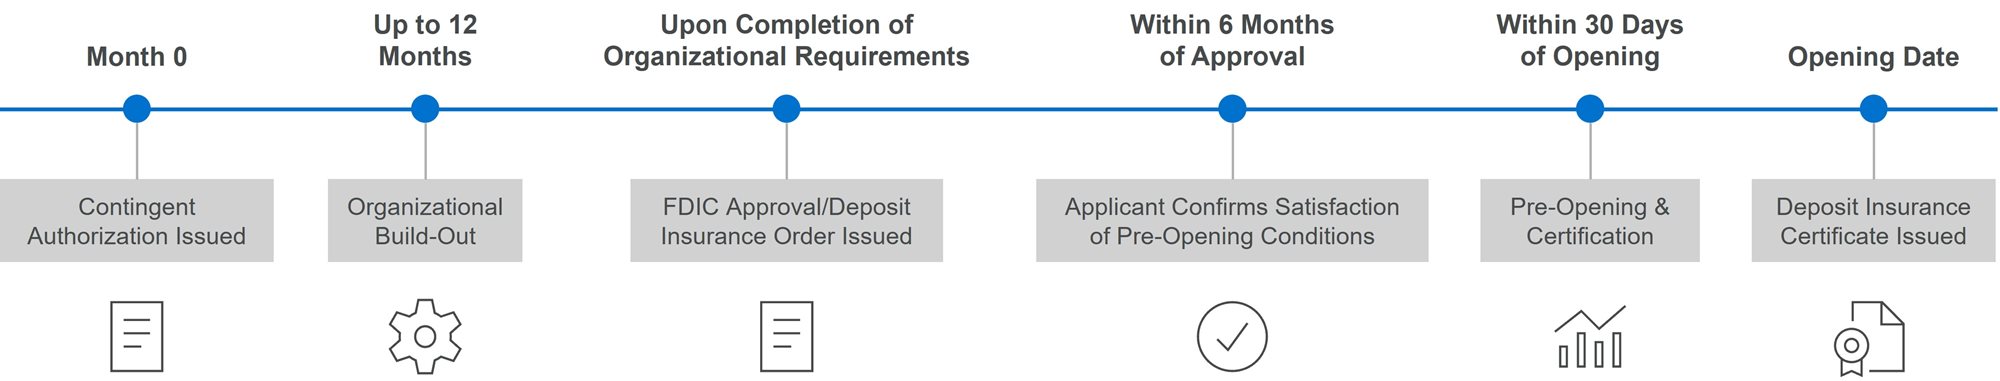
The sequencing is the key point here. Applicants now learn whether their proposal has cleared the substantive threshold before they commit the bulk of their capital and time to building the institution. Three separate milestones now mark the path: the contingent authorization letter, the deposit insurance order, and the deposit insurance certificate.
Faster Does Not Mean Easier
The compressed calendar should not be mistaken for a lowered bar. The seven statutory factors the FDIC must weigh under Section 6 of the Federal Deposit Insurance Act (FDI Act) remain unchanged and are not relaxed by the new timeline. What changes is the discipline the timeline imposes on both sides.
The 120-day application review timeline is not new as the FDIC has maintained a 120-day processing goal for deposit insurance filings for decades, most recently reiterating that goal in 2018. What is new is where the clock starts. The prior goal ran from the date staff accepted a filing as substantially complete; the revised procedures run 120 calendar days from receipt. To reach a decision in 120 days, the FDIC expects a filing that is substantially complete on arrival and an applicant that responds to information requests with minimal delay. The burden of preparation shifts forward. As such, the front-loaded model rewards those that invest in a credible, well-documented package before a filing is submitted.
Contingent authorization carries no guarantee that a deposit insurance certificate will be granted. The FDIC can still decline final approval, and the conditions embedded in the deposit insurance order continue to govern whether and when the institution may open.
The Office of the Comptroller of the Currency (OCC) has reinforced this expectation in practice. In Bulletin 2026-27, issued in June 2026, the OCC committed to publishing its de novo denial decisions, and the denial letters released in July and August 2026 each faulted organizers for leaving critical work such as capital formation, management hiring, and infrastructure build-out, unfinished until after approval. The lesson for applicants under the FDIC’s front-loaded model is the same, a contingent authorization rewards readiness, not intentions.
Closing the Gap Between Charter & Insurance
Historically, organizers navigated deposit insurance and chartering as parallel processes, an approach that created synchronization gaps, duplication, and extended timelines. The FDIC’s revised procedures address this directly.
The agency now expects that applicants will file concurrently with both the FDIC and the chartering authority, i.e., the OCC or a state regulator, with limited exceptions, and commits to coordinating throughout the review. The new design mirrors the OCC’s two-phase conditional approval model. For a prospective national bank, the two federal review processes should now move together, reducing the risk that progress stalls on one side while open questions are addressed on the other. The revised procedures also direct that all information, including meeting materials and responses to information requests, be provided simultaneously to the FDIC and the chartering authority where possible.
A Charter-Neutral Framework
The procedures are charter-neutral and do not single out or appear to disadvantage any institutional form, which is notable for industrial loan companies (ILCs) that run through an FDIC deposit insurance application rather than a federal charter. The FDIC stated in the FIL that it welcomes applications from all types of proposed insured depository institutions that can present a viable business plan consistent with favorable resolution of the statutory factors. As it stands, the reforms extend the same front-end clarity to an ILC applicant that they extend to any other charter applicant.
However, that clarity addresses process rather than disposition. The defined timeline does not resolve the substantive questions that have accompanied ILC applications, including separation of the bank from a commercial parent, the parent serving as a demonstrated source-of-strength, and the governance independence of the formed entity.
Implications for Institutions & Prospective Entrants
For organizers, the practical value of the update is that optionality is preserved. The contingent authorization arrives before the most capital-intensive commitments are made, giving them an early view into the viability of their proposal before they raise equity, sign leases, or undertake larger infrastructure build-out. The corresponding expectation is readiness at filing.
Prospective entrants should treat pre-filing engagement with the FDIC and the chartering authority as a core step. The pre-filing meeting is where the FDIC assigns a dedicated case manager to serve as the organizers’ primary point of contact. Applicants should arrive with financial projections and assumptions that withstand supervisory scrutiny and secure management and board depth that extends beyond a single founder. In addition, a realistic planning horizon still matters. Even under the new framework, the combined phases can extend well beyond 18 months from filing to opening for some applicants: 120 days to contingent authorization, up to 12 months of organizational work, and up to six more months from approval to issuance of the deposit insurance certificate. And this timeline does not include the time spent prior to the application.
Existing banks, especially community banks, have reason to watch the application pipeline. The OCC alone reported receiving 40 de novo applications in the 18 months preceding the announcement of the FDIC’s revised procedures. This compares to 48 applications the OCC received in the 14 years from 2011 through 2024. The recent wave of application submissions and potential increase in de novo formation would introduce increased competition for talent, deposits, and lending relationships. At the same time, the statute that streamlines entry also lowers funding costs for community banks through its deposit provisions, so the net effect on competition could vary by market.
What to Watch
While the revised procedures provide more clarity around process, they nonetheless raise three new issues. First, does the 120-day window toll? While the review clock runs from the date of receipt, an additional information request may be issued on day 30, and background checks may extend beyond phase one by the procedure’s own terms, yet nothing states that the clock stops for any of it. Second, what happens when a contingent authorization is not warranted? The 120-day deliverable is a contingent approval letter “if warranted,” and no alternative outcome is described, no mention of an automatic denial, no mention of an extension, and no mention of a return of the filing. Third, where has “substantially complete” gone? The phrase does not appear in the new framework but remains operative in the “Deposit Insurance Applications Procedures Manual,” where acceptance is expressly delayed until deficient materials arrive. How the agency answers these will determine whether 120 days is truly a commitment or merely an aspiration.
How Forvis Mazars Can Help
The FDIC’s two-phase review reflects a concerted effort to make entrance to banking more predictable without necessarily opening it wider. It substitutes indefinite processes with a defined, sequenced timeline, front-loads the weight of diligence, and moves deposit insurance more closely to chartering. For organizers, preparing earlier and comprehensive planning is imperative.
The bank charter application process is a rigorous journey that demands meticulous planning, due diligence, and proactive stakeholder engagement. Our De Novo Bank Charter offering provides an application readiness assessment, tailored training and workshops, and end-to-end filing support to help your institution navigate the regulatory demands. By combining our capabilities, we help turn the bank charter application process from a daunting regulatory hurdle into a streamlined path toward operational launch and sustainable growth.
Reach out to a professional at Forvis Mazars for questions or assistance.