
Healthcare leaders are planning for 2027 with tighter margins, shifting reimbursement, and rising expectations for AI. In the Mindsets 2027 Healthcare Industry Outlook, we surveyed more than 230 healthcare executives nationwide to learn where they see risk, where they plan to invest, and how they intend to move forward across the core capabilities for achieving health outlined in our Healthcare Market Point of View.
Why This Outlook Matters Now
The decisions you make in the next two years will shape your organization’s performance for the next decade. Leaders across the continuum of care are facing that reality today.
They’re rethinking cost structures. They’re pursuing new paths to growth. They’re deciding how far and how fast to scale AI.
The Mindsets 2027 Healthcare Industry Outlook offers a clear view of how your peers are responding to pressure and preparing their organizations for what’s next.
What Concerns Healthcare Executives Heading Into 2027?
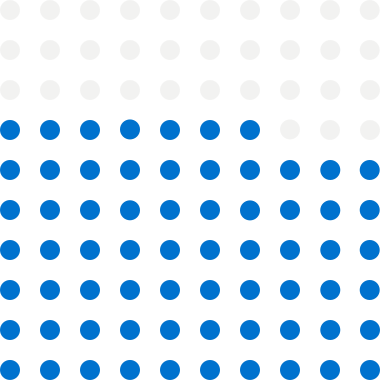
Regulatory and reimbursement restructuring is the leading market concern for 2027, cited by 67% of executives.
Organizations face growing pressure from Medicaid eligibility and funding restrictions, changes to Medicare Advantage reimbursement and utilization management, and other evolving federal healthcare regulations.
Other top concerns include talent and workforce challenges, payor mix, and economic uncertainty. These pressures don’t exist in isolation. They compound and demand a coordinated response.
What Are the Biggest Strategic Priorities for Healthcare Organizations in 2027?
Short-term margin pressure is pushing leaders to strengthen their operational efficiency over the next two years to improve cost structure. Key areas for improvement include:
- Revenue cycle management
- Workforce productivity
- Cost reduction
After the two-year mark, growth and access move to the top of the priority list. Leaders aim to relieve margin pressure through topline growth.
Executives expect consolidation to accelerate. Many organizations will pursue mergers, acquisitions, partnerships, affiliations, and joint ventures to support financial sustainability.
Organic growth remains a priority as well. Top capital investment priorities include IT systems, digital health platforms, and outpatient care facility expansion.
Efficiency builds the foundation. Growth builds the future.
How Are Healthcare Executives Approaching AI Adoption & Integration?
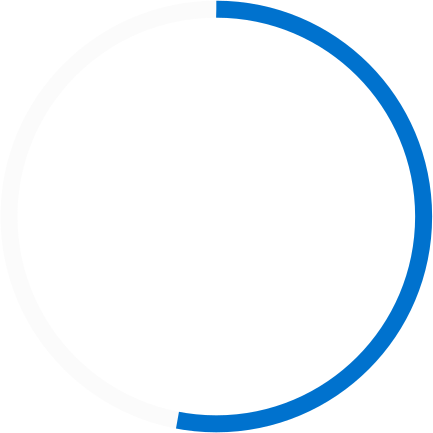
More than half expect AI will improve labor productivity, revenue cycle performance, and cost reduction.
Healthcare leaders see strong potential for AI to help improve operational efficiency and talent optimization. A growing number now ranks AI and automation as a top priority in both the short and long term.
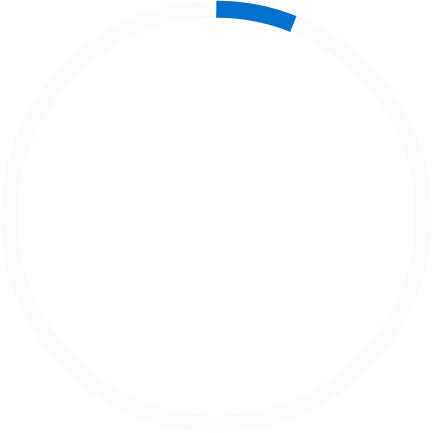
Only 6% have a data governance process optimized for AI deployment.
AI readiness is a different story. Most organizations have begun developing data governance processes, but only a small number say those processes are optimized. In addition, fewer than 25% have begun scaling AI deployment across the enterprise.
What You’ll Learn in the Full Report
The full Mindsets 2027 report goes deeper into the challenges, priorities, and trends shaping healthcare. Inside, you’ll discover:
- How reimbursement and regulatory excellence are influencing enterprise design decisions
- Why aligned growth is becoming a necessary resilience capability
- How execution and financial discipline determine value realization
- Why AI deployment requires strategic agility to improve enterprise productivity
- How talent optimization makes the physician enterprise an organizational performance lever
Be Among the First to Receive the Full Mindsets 2027 Report
The full Mindsets Healthcare Industry Outlook arrives in January 2027. Sign up today to reserve your complimentary copy. We’ll email you as soon as it’s available.
About the Mindsets 2027 Survey
Mindsets is an annual survey and report from the Healthcare Practice at Forvis Mazars. Our team designs and curates the survey questions based on years of work with healthcare organizations and direct client feedback.
We field responses in collaboration with Gerson Lehrman Group (GLG). Participants are qualified through demographic screening questions about their role and organization.
Survey Demographics
- 236 executives from nonprofit, for-profit, and private equity-backed provider organizations
- C-suite, senior vice president, or vice president roles only
- 29 states across the U.S.
- Organization types represented: